The Pacific nation has cut its anti-money laundering compliance burden from 75 items to 18. But with international banks watching and billions in trade flows at stake, completing the list is only half the battle.
Papua New Guinea has reduced its outstanding Financial Action Task Force compliance obligations to just 18 remaining action items, government officials have confirmed — a significant milestone in the country’s effort to exit one of global finance’s most consequential watchlists.
The number is down from 75 when Papua New Guinea was formally placed under increased FATF monitoring in February 2026. That’s a completion rate of more than 75 percent. On paper, PNG is closer to financial rehabilitation than at any point since the process began.
But finishing the list and actually getting off it are two different things.
What the Grey List Is — and Why It Costs PNG Real Money
The FATF grey list — officially “Jurisdictions Under Increased Monitoring” — is not a sanctions regime. FATF, established by the G7 in 1989, does not freeze assets or block transactions. What it does is signal risk. And in global banking, risk signals have price tags.
Countries on the list face heightened due diligence requirements from correspondent banks. Cross-border transactions take longer and cost more. Remittance flows — which many Pacific households depend on — become more expensive to process. Trade financing gets more scrutinous. Foreign investors apply a grey-list discount to any deal they’re considering.
PNG was first grey-listed in 2015, then exited. It returned to the list in February 2026 following a FATF plenary decision that identified persistent gaps in the country’s anti-money laundering and counter-terror financing architecture. The decision was not unexpected — PNG’s financial sector regulators had acknowledged deficiencies in enforcement effectiveness for several years before the formal listing.
23 Agencies, One Action Plan, and a Countdown Clock
Since February, the Bank of Papua New Guinea has co-chaired a National Coordinating Committee on AML/CFT/CPF — an interagency body that brings together 23 government institutions responsible for enforcement, supervision, intelligence, prosecution, and policy coordination.
The scale of that coordination is not trivial. Getting 23 agencies aligned on a common reform agenda, moving at the same pace, and reporting credible progress to an international body is an institutional challenge that most countries underestimate when they first enter the process.
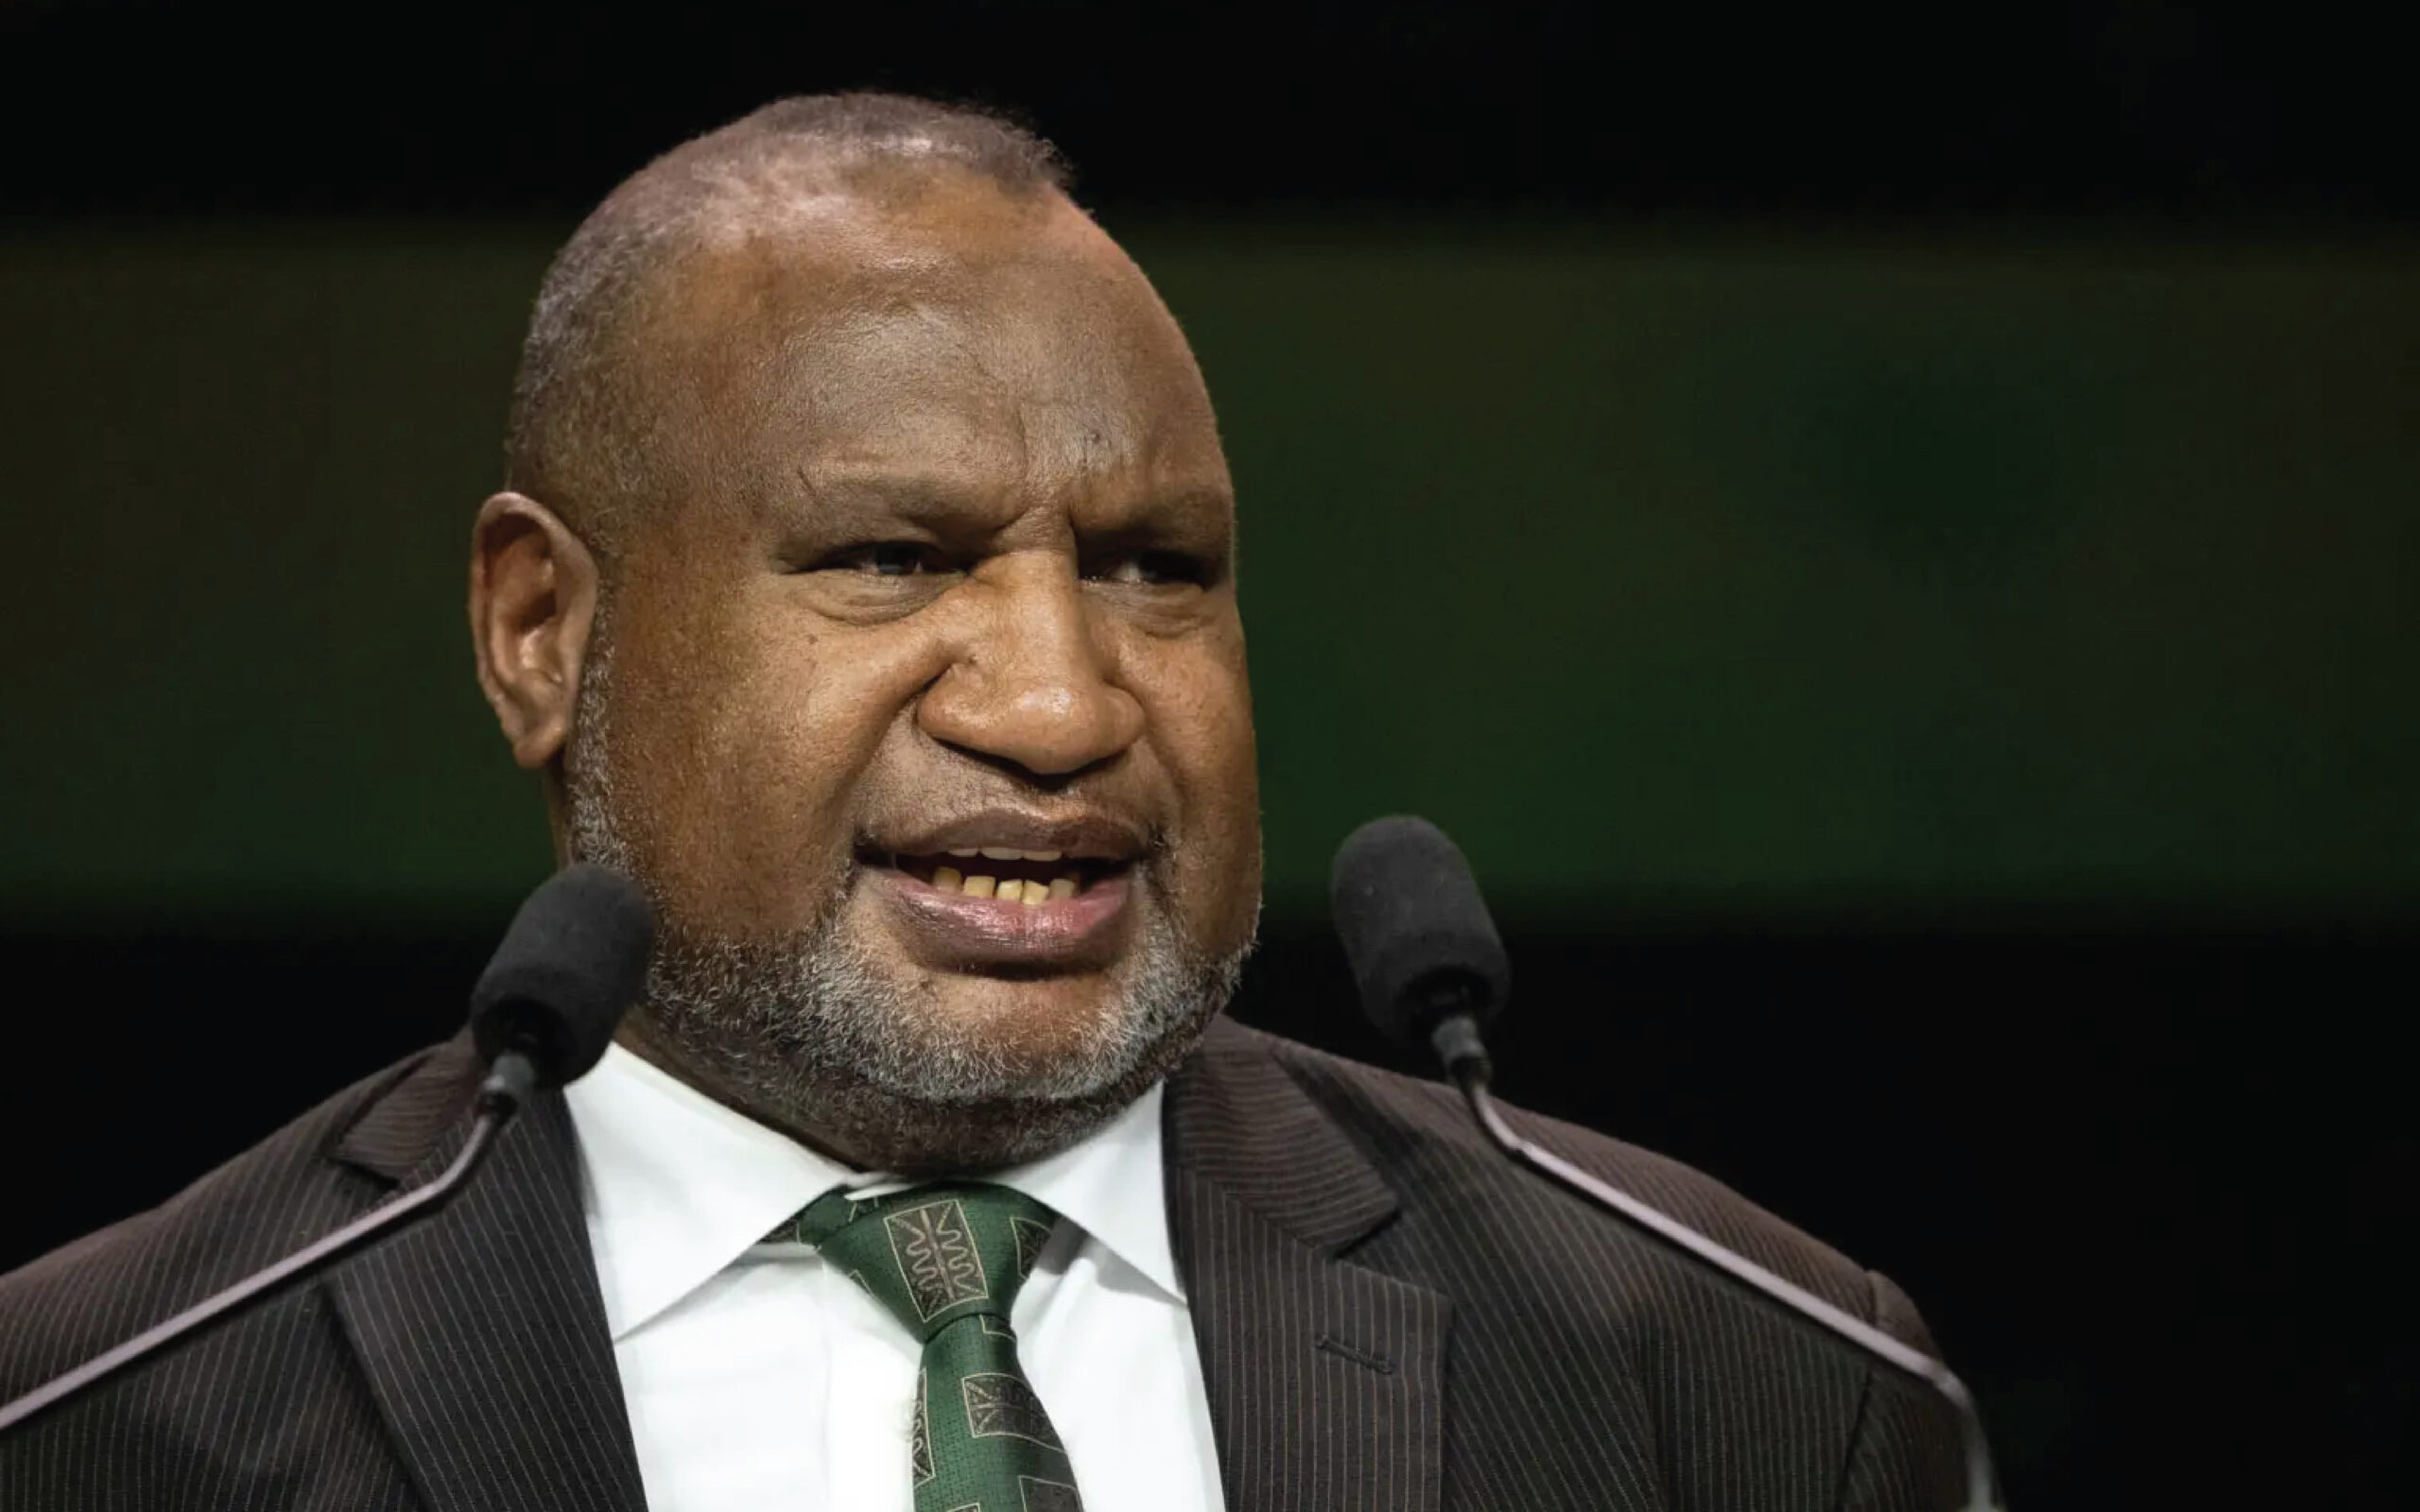
Prime Minister James Marape has publicly stated that PNG is better positioned now than during its 2015 grey-listing. He’s pointed to a decade of institutional reform that has, according to his government, built meaningful compliance capacity across the financial system. Officials have framed the current effort as a whole-of-government reform push rather than a technocratic exercise run out of the central bank.
That framing matters. FATF’s review process is not just about whether laws exist on paper. It assesses whether those laws are being applied — whether regulators are catching violations, whether prosecutors are winning cases, whether illicit assets are actually being recovered.
The 18 That Remain — and What They Cover
The outstanding 18 recommendations are not the easy ones. Typically, countries completing FATF action plans knock out the legislative and administrative items first — the ones that require passing a law, establishing a unit, or signing an MOU between agencies. What tends to remain are the operational requirements: prosecution rates, asset recovery outcomes, enforcement effectiveness data, and demonstrated improvements in inter-agency intelligence sharing.
That’s the terrain PNG is now working through. Official updates describe the remaining benchmarks as spanning legal reforms, regulatory improvements, enforcement outcomes, and international cooperation standards. Each will require not just institutional action but documented, verifiable results that FATF reviewers can assess in scheduled reporting cycles.
The Banking System’s Exposure
For PNG’s financial sector, exit from the grey list carries direct commercial consequences. Correspondent banking relationships — the agreements that allow PNG banks to clear transactions in foreign currencies through international banking partners — are sensitive to FATF status.
Several Pacific nations have faced correspondent banking pressures in recent years, with international banks reducing or restructuring their PNG exposure in response to compliance risk perceptions. A sustained period on the grey list risks accelerating that trend. For a country that depends on imported goods, commodity export receipts, and development finance from international partners, correspondent banking access is not an abstraction — it is plumbing that the entire economy runs through.
What Governance Observers Are Watching
Transparency International PNG and regional governance bodies have consistently flagged that enforcement effectiveness — not legislative adequacy — is where Pacific AML regimes tend to fall short. Passing laws is achievable within political cycles. Prosecuting the people those laws are designed to catch is a different institutional capability entirely.
The question for PNG’s reform agenda is whether the 23-agency coordinating structure can sustain operational momentum beyond the political calendar. FATF reviews run on their own timetable. The next scheduled assessment will test not what PNG committed to doing, but what it can prove it has done.
What an Exit Would Mean
A successful exit from the FATF grey list would be one of the most significant financial governance milestones PNG has recorded in years. It would signal to international banks, development finance institutions, and foreign investors that the country’s financial system meets global compliance standards.
It would also validate the whole-of-government reform model — a meaningful proof of concept that 23 agencies can coordinate at pace on a shared international accountability framework.
The economic dividend would follow. Correspondent banking relationships could normalise. Remittance costs could ease. Investment due diligence processes for PNG-linked deals could become less burdensome. For a country actively courting foreign capital across mining, energy, infrastructure, and digital sectors, that shift in risk perception would carry real value.
The Question No One Can Answer Yet
Eighteen items. Multiple agencies. A FATF review cycle that waits for no one.
PNG has shown it can cut compliance requirements by more than three-quarters. Whether the final stretch — the enforcement-heavy, outcome-dependent, institutionally demanding final stretch — gets cleared before the next review is the question that will define how this chapter ends.
Progress is real. But in the language of financial compliance, real progress and proven effectiveness are not the same sentence.