ANZ Cash Profit Jumps 31% to A$7.59 Billion as Matos Cuts Costs
ANZ lifted full-year cash profit 31% to A$7.59 billion as chief executive Nuno Matos booked A$902 million in savings and held the dividend at 166 cents.
Key points
- ANZ lifted cash profit 31% to A$7.59 billion in the year to 30 September 2026, or 10% excluding significant items booked in 2025.
- Chief executive Nuno Matos said all five ANZ 2030 priorities are on track after A$902 million in productivity savings cut the cost-to-income ratio to 49.26%.
- Collective provision charges rose A$108 million as financial pressure on some Australian customers grew in the second half.
ANZ Group Holdings (ASX: ANZ) lifted cash profit 31% to A$7.59 billion in the year to 30 September 2026, according to the bank’s full-year results release on Monday. Excluding significant items booked in 2025, cash profit rose 10%. Cash profit is the bank’s preferred measure and strips out non-core items included in statutory profit, the release said.
Statutory net profit reached A$7.27 billion, up 23% on the prior year, Michael West Media reported. The Australian Financial Review reported that the cash result met expectations.
ANZ said cash return on tangible equity rose 109 basis points to 11.56%. Its Common Equity Tier 1 ratio was 11.99% at 30 September, down 4 basis points from a year earlier. ANZ said the capital position absorbed the impact of higher term rates and its acquisition of ANZ Worldline.
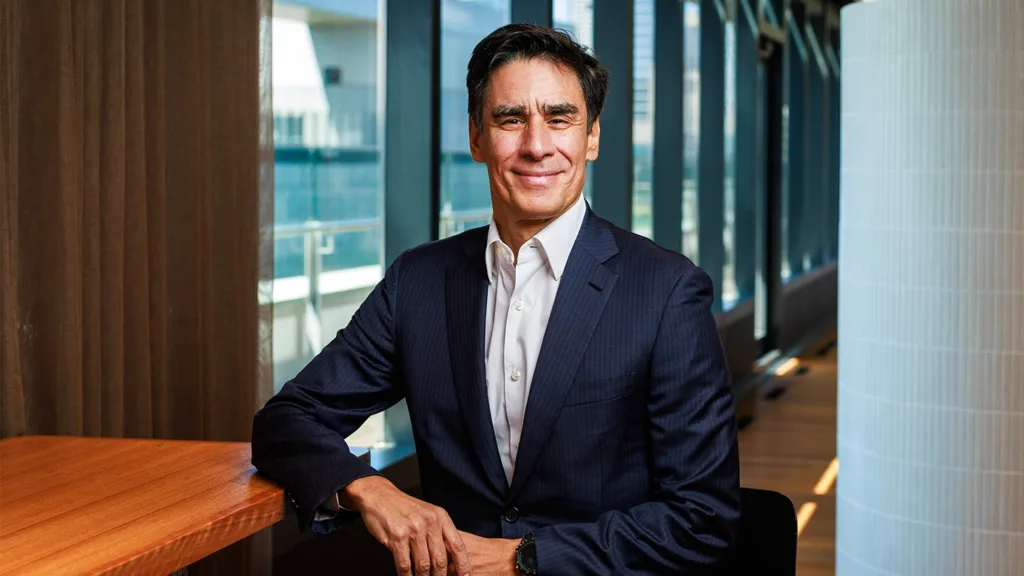
The result is the first full financial year under chief executive Nuno Matos, who joined ANZ in May 2025 and released the ANZ 2030 strategy five months later, according to Michael West Media.
Matos said the bank was on track to deliver all five immediate priorities under the plan on time, while investing in growth initiatives. He said business execution was improving quarter on quarter.
“Our transformation is happening – and we have momentum,” Matos said.
ANZ holds dividend at 166 cents
The board declared a final dividend of 83 cents a share, matching the interim payment, according to the release. The full-year payout of 166 cents was in line with fiscal 2025, Michael West Media reported.
Franking rose to 80% from 75% in the first half. ANZ attributed the increase to continued improvement in its Australian business. The interim dividend had already lifted franking from 70%.
ANZ said the dividend reinvestment plan will carry no discount and will be neutralised through an on-market purchase of shares.
Savings beat the A$875 million target
ANZ reported a productivity benefit of A$902 million for the year. That exceeded the A$875 million in gross cost savings the bank flagged at its first-half result.
The cost-to-income ratio improved by more than 4 percentage points to 49.26%, according to the release.
Matos said the bank had embedded a new leadership team and begun a cultural reset. The changes included new values and an updated Code of Conduct, which he said gave staff clarity on “the behaviours, decisions and pace expected of them.”
Bad debt charges rise at ANZ
The total credit impairment charge was A$582 million, ANZ reported. The individual provision charge rose A$33 million to A$360 million, an annualised loss rate of 4 basis points, unchanged from 2025.
The collective provision charge climbed A$108 million to A$222 million. ANZ linked the rise to portfolio growth and to emerging risk as higher interest rates and living costs weighed on customers.
The collective provision balance grew A$151 million to A$4.53 billion. ANZ said it holds A$2.1 billion above its base economic scenario. The ratio of collective provisions to credit risk-weighted assets rose 2 basis points to 1.20%. Non-performing exposures held at 0.57% of total credit exposure.
Matos said most Australian retail customers were ahead of scheduled repayments. He said ANZ was also helping small and medium-sized businesses weather a more challenging environment.
He described an external environment shaped by geopolitical tensions, energy price shocks and rapid technological change. Competition for capital to fund data centres, government spending and the energy transition was pushing interest rates higher globally, he said.
ANZ’s international network spans 29 markets, according to Matos. The bank is working with large corporate clients on funding, hedging and supply chain finance tied to Asia’s technology-led export boom.
Matos said the loan book is mostly made up of investment-grade or highly secured wholesale customers and well-secured mortgage customers.
Funding and liquidity
The average liquidity coverage ratio was 132% and the net stable funding ratio 116% at 30 September, both above regulatory minimums, the release showed.
ANZ issued A$25 billion of term wholesale debt in the second half. That took the full-year total to A$40 billion. Matos said the bank draws on diverse funding from both depositors and debt investors.
Suncorp Bank deadline set for June 2027
ANZ said it remains on track to complete the integration of Suncorp Bank by June 2027. A single customer front-end for retail and small business customers is due by September 2027.
The bank released the second and third reports from Promontory, the independent reviewer of its Root Cause Remediation Plan. ANZ said it reports regularly to its board and to the Australian Prudential Regulation Authority on the plan. It also cited progress under its ASIC Matters Resolution Program.
Matos called 2027 “pivotal” for ANZ, with the two transformation projects due three months apart. He said the year would also bring a significant uplift and investment in capabilities through the bank’s growth initiatives.
ANZ’s next hard deadline is June 2027, when the Suncorp Bank integration is due for completion.